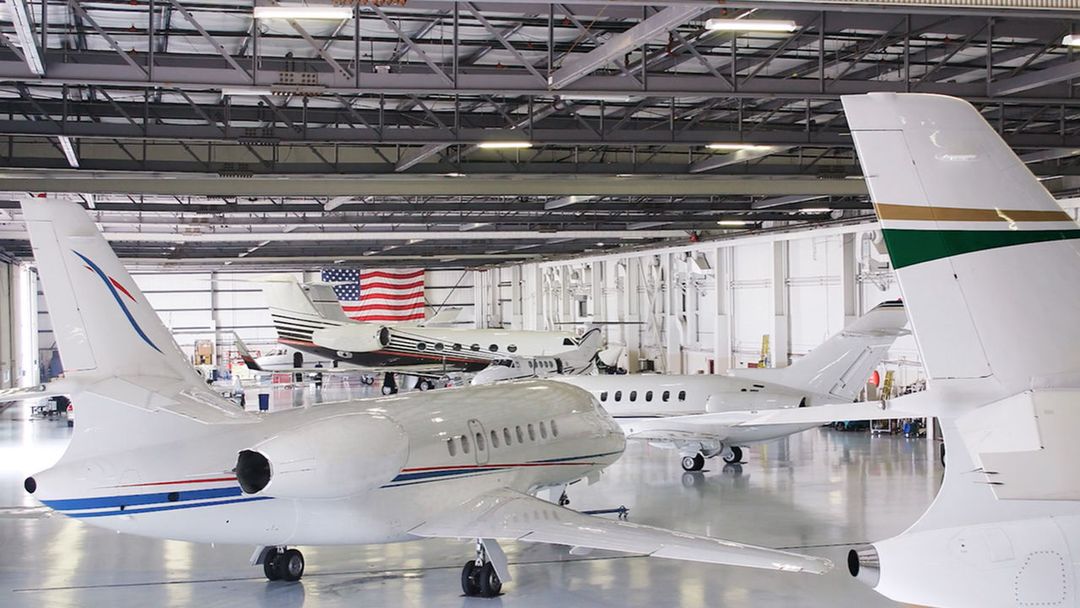
KKR turned a $4.5 billion private aviation investment into a nearly $10 billion asset. The workforce data I have dug into shows how this is already changing the game for the PJ sector.
While some believe that KKR’s investment in Atlantic Aviation as the K-shaped economy on full display… I had almost the opposite reaction. I thought the investment and results was kind of genius.
I don’t look at it like ‘oh, more wealthy people are flying private’, and I don’t view this as private equity executed another roll-up. Honestly, what caught my attention was the structure of the bet. KKR did a roundabout thing here… they didn’t buy the aircraft manufacturer, the fractional operator or the charter company, they bought infrastructure like fuel, hangars, ramp space, ground handling and airport access. It might have even bought time.
KKR acquired Atlantic from Macquarie Infrastructure in 2021, and at that time, Atlantic operated 69 locations and generated $276 million of EBITDA in 2019. KKR paid 16X times that EBITDA, so frankly, this wasn't some distressed asset picked up on the cheap at all. Atlantic also came with something less obvious on a financial statement:these are businesses built on long-duration, hard-to-replace leases.Macquarie's own disclosures, going back to when it first built out the platform, had described the structural barriers surrounding the FBO business. The thing that gets overlooked is that airports have finite physical space, airport authorities control development and competition, new facilities require substantial capital, and another operator cannot simply open across the street when the economics get attractive. That didn't stop KKR paying a premium for scarcity.The interesting thing here is that they spent the next 5 years making scarcity productive.